Accounts and Subscriptions to Close After a Death
Subscriptions, memberships and online accounts to cancel or transfer, with the monthly cost of whatever is still running.
- Excel
- Works in Google Sheets
Included in The Executor Kit ($39), with 7 other files.
Instant download. One payment. 14-day refunds.
What this is for
Most people now pay for a handful of services they rarely think about: a streaming plan, cloud storage for photos, a newspaper, a gym, an app that renews once a year. After a death, these keep charging the card or bank account until someone cancels them. Each one is small, but together they can add up to a real monthly amount, and some hold things the family will want to keep, such as photos, emails or a music library.
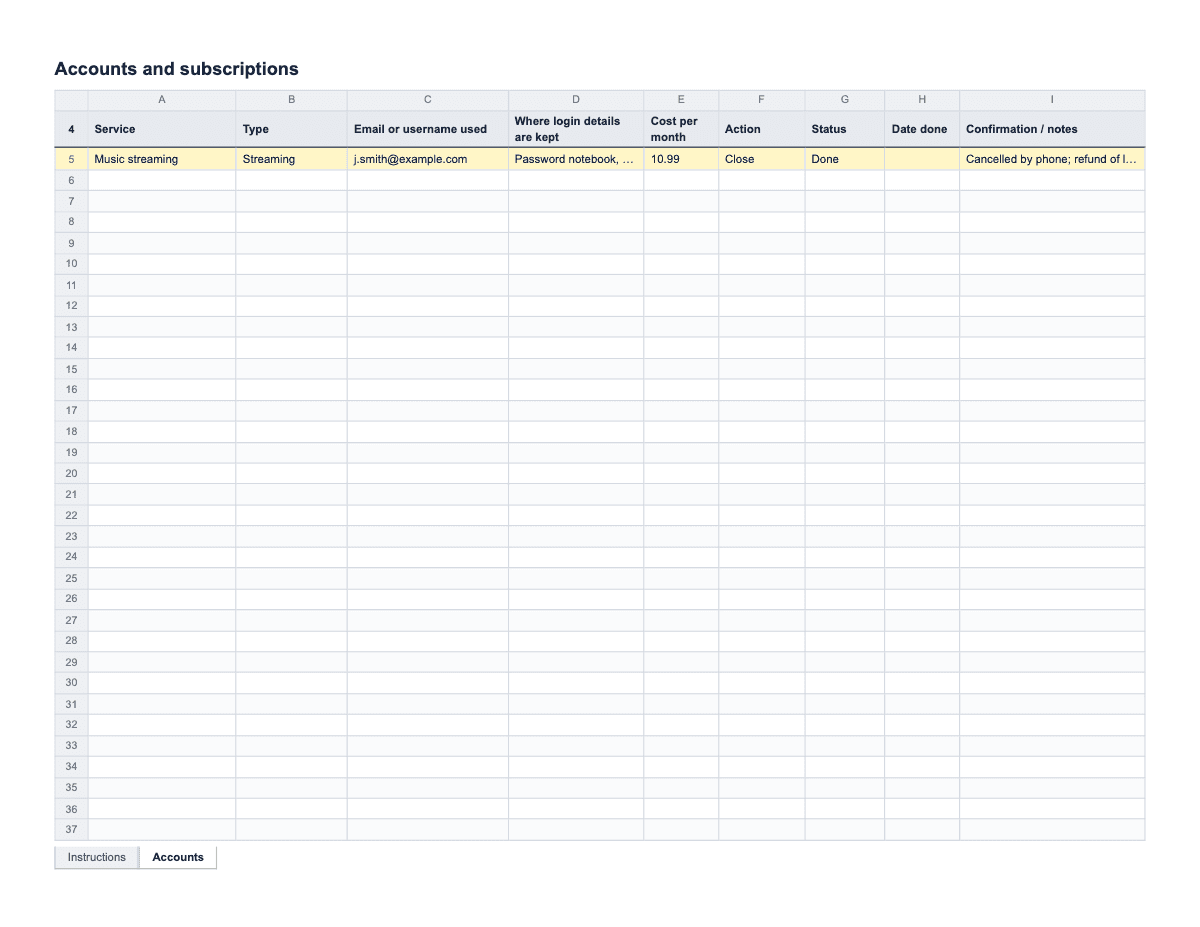
This spreadsheet gives you one list to work through. The Accounts tab has a row for each service, with columns for Service, Type, Email or username used, Where login details are kept, Cost per month, Action, Status, Date done and Confirmation / notes. At the top, a running total shows how much is still being charged each month by everything that has not been dealt with yet, so you can watch that figure fall as you go.
The Type dropdown covers Streaming, Phone, Email, Social media, Shopping, Software / apps, Cloud storage, Magazine / newspaper, Gym / club, Charity donation, Loyalty / rewards and Other. The Action dropdown has four choices: Close, Transfer, Memorialize (for social media sites that offer it) and Keep for now. The file deliberately has no column for passwords. It asks only where the login details are kept, such as a password manager or a notebook in a desk drawer, because a spreadsheet shared with family is not a safe place for them.
How to fill it in
- Open the file, read the instructions tab, and delete the EXAMPLE row on the Accounts tab before you start.
- Find the subscriptions. The most reliable source is the last three to six months of bank and credit card statements: look for small repeating charges and annual renewals. Their email inbox, if you can reach it, often has receipts and renewal reminders. App store purchase histories on a phone or tablet are another place to look.
- Add one row per service. Fill in Service and Type, then Email or username used so the company can find the account. In Where login details are kept, write a location, not a password.
- Enter Cost per month. For a yearly plan, divide the annual price by twelve so the total at the top stays meaningful. Leave it blank for free accounts such as email or social media.
- Decide on the Action for each one. Close for paid services nobody needs. Transfer for accounts a family member will take over, like a phone line or a shared streaming plan. Memorialize for social media profiles where the family would like the page kept as a memorial. Keep for now for anything you are unsure about, such as an email account you still need to receive statements.
- Contact each company. Many have a bereavement page or form; some ask for a death certificate or proof that you are the executor. Set Status as you go: In progress, Waiting, then Done. Enter the Date done and write any confirmation number in Confirmation / notes.
- Keep an eye on the monthly total at the top. When a row is marked Done or Not needed, its cost drops out of the total. If a charge still appears on the next statement, set the row back to In progress and call again.
- For larger organizations such as banks, insurers and utilities, use the who to notify list instead. Services that insist on a letter can be sent an adapted version of the death notification letters.
A filled-in example
| Service | Type | Where login details are kept | Cost per month | Action | Status | Confirmation / notes |
|---|---|---|---|---|---|---|
| Music streaming | Streaming | Password notebook, desk drawer | $10.99 | Close | Done | Canceled by phone 04/03. Refund of last month offered. |
| Photo cloud storage | Cloud storage | Phone, saved in browser | $2.99 | Keep for now | In progress | Downloading photos first. Close once copied. |
| Mobile phone line | Phone | Paper bill, kitchen file | $45.00 | Transfer | Done | Number moved to daughter Emma’s plan, ref 88213. |
| Sports newspaper | Magazine / newspaper | Email inbox | $8.50 | Close | In progress | Canceled 04/05 but charged again 05/05. Called 05/08; refund promised, ref C-4471. |
| Social media profile | Social media | Not known | Memorialize | Waiting | Request sent with death certificate 04/12. |
Common mistakes
- Closing the email account too soon. Their inbox may be the only place that shows which services they used, and some companies send the final bill or refund confirmation there. Keep it for now if you can reach it.
- Canceling cloud storage before copying photos and documents. Once an account is closed, its contents may be deleted. Download what the family wants first.
- Writing passwords in the spreadsheet. The file is often shared with several people. Record where the login details are kept, and keep the details themselves somewhere safer.
- Canceling the card before the subscriptions. It feels quicker, but charges can then fail silently while the account stays open, and you lose the easiest record of what was being paid. Cancel each service, then deal with the card.
- Not writing down confirmation numbers. When a charge appears again next month, a date and a reference number turn a long call into a short one.
What the rules say
The IRS advises sending the credit bureaus a copy of the death certificate, asking for a deceased alert on the person’s credit reports, and keeping personal details out of the obituary.
Source: IRS, Identity theft guide for individualsBeing reviewed
A person’s debts are generally paid from what they leave behind (their estate). You are not responsible for them unless you shared the debt, for example as a co-signer or joint account holder, or another exception applies.
Source: CFPB, Does a person’s debt go away when they die?Being reviewed
Last reviewed September 29, 2026. We link to official sources; your local rules may differ, so check them.
Questions
- How do I cancel subscriptions after someone dies?
- Find them on recent bank and card statements, then contact each company. Many have a bereavement or account holder deceased page. They may ask for a death certificate and proof that you are the executor. Keep a note of each cancellation and check the next statement to make sure the charge has stopped.
- What happens to social media accounts when someone dies?
- It depends on the platform. Some let family members request that an account be memorialized, which keeps the profile visible but stops anyone logging in; others offer closure only. Check each site’s help pages, which usually explain what documents they need.
- Should I log in to their accounts with their password?
- Be careful. Many services’ terms say accounts are personal, and logging in as someone else can cause problems. The safer route is usually to contact the company as the executor or next of kin. If you are unsure, ask a probate attorney.
- Can I get a refund for charges after the date of death?
- Sometimes. Some companies refund the last payment or a partial period when told about a death; others do not. It is always worth asking, and the Confirmation / notes column is the place to record what they agreed.
- How do I stop someone’s identity being used after they die?
- The IRS advises sending the credit bureaus a copy of the death certificate, asking for a deceased alert on their credit reports, and keeping personal details out of the obituary. Closing unused online accounts also reduces the number of places their information sits.
- Do subscriptions count as estate debts?
- Unpaid charges up to the date of death are usually handled like other bills: the CFPB says debts are generally paid from the estate, and you are not personally responsible unless you shared the account. Record any unpaid balance on the estate inventory spreadsheet so the executor can deal with it alongside other debts.